Palomma raises US$14 million with Cometa to build a digital bank for rent
Palomma raised US$14 million in a round led by Cometa to consolidate its rent payment and AI platform in Colombia and expand across the region.
Katherine CastelánStartuplinks
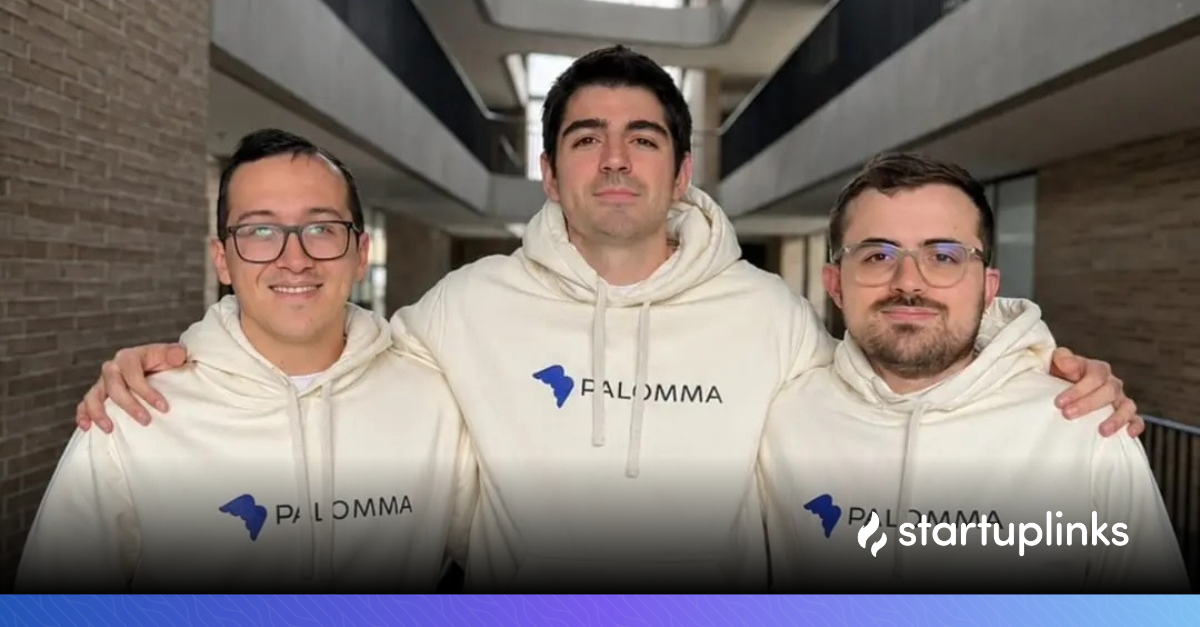
Palomma, a Medellín-based startup that combines artificial intelligence and financial services for the rental market, announced on November 11, 2026, that it had raised US$14 million. The total combines a US$10 million Series A led by Mexican firm Cometa with US$4 million in previously undisclosed financing, its co-founder and CEO confirmed to Crunchbase News. Cometa, formerly known as Variv, is a Mexico City-based fund that has invested in early-stage Spanish-speaking startups since 2012 and has companies such as Bitso and Kueski in its portfolio. Volpe Capital, Clocktower, Tekton, Simma, and Yango Ventures participated in the deal, while Y Combinator, Nido, Norte Ventures, and 17Sigma—the investment vehicle of Ualá founder Pierpaolo Barbieri—reinvested. The company was founded by Cipriano Echavarría (CEO), Felipe Monsalve (CTO), and Nicolás Gómez del Campo, who leads AI.
In about 18 months, its annual recurring revenue grew from US$100,000 to around US$3 million; it processes around US$130 million in rent payments each month and connects more than 500 real estate agencies with 200,000 tenants. The company also reports 390% net revenue retention over 12 months and operates with a team of 18. Its stated goal with the new capital is to double its operations in Colombia over the next 12 months. Palomma is also seeking to finalize a partnership with an insurer to share the risk of its rental guarantees, which it currently assumes on its own. Only then does it plan to enter Mexico, Brazil, and the Spanish-speaking US market.
The fintech went from a payment button to collecting rent and financing itself with that data
Palomma joined Y Combinator in January 2023 with an account-to-account payment processor and focused on the rental market in early 2024. Today, it distributes its services through real estate agencies, which pay a subscription for software that automates rental conversations, customer service, and collections on channels such as WhatsApp; by processing payments, the company builds its own transaction history to assess the risk of its financial products. On that basis, it offers Palomma Advance, which advances landlords up to 12 months of rent, and Palomma Protect, a guarantee that covers rent for up to 36 months if a tenant defaults. The founders’ diagnosis is a liquidity mismatch: tenants are usually paid every two weeks, but pay rent in a single installment at the start of the month.
The margin comes from these financial products, not collections: of the monthly volume it processes, the company retains around 0.2%. Its main competitors are traditional financial groups such as Grupo Aval and Grupo Bolívar. For Cometa, the advantage lies in combining distribution, proprietary payment data, and AI—an advantage that should grow with scale. The timing also suits Volpe Capital: the São Paulo fund held the first close of its second vehicle in March 2026, raising US$50 million, and its partner Gabriel Marcassa said it would expand its focus to Mexico and Colombia because of the presence of more mature companies with more reasonable valuations.
Volpe Capital sees rental housing as a large, under-innovated industry
“Palomma has the potential to lead that transformation.”
— Gabriel Marcassa, partner at Volpe Capital
Rent is Latin America’s largest and most recurring real estate cash flow
The region’s real estate sector moves around US$565 billion a year in financial flows, and rent is its largest and most recurring segment, at around US$205 billion. Palomma’s thesis applies the digital banking playbook to a single vertical: use real estate agencies as a channel and payments as a source of data to offer credit and liquidity to tenants and small landlords without a credit history. If the model works beyond Colombia, it would open up a space that traditional banks have served with manual processes and requirements for co-signers.
Colombia is a natural testing ground: according to DANE, 41% of households rent their homes, the highest rate in Latin America, equivalent to around 8 million households and an annual flow of more than US$30 billion.
The monetary environment is both a tailwind and a headwind. In early November 2026, Banco de la República kept its policy rate at 12.25% because inflation remains far from its target. Expensive bank credit makes rent advances attractive to landlords, but also raises funding costs for a fintech that advances liquidity using its own balance sheet.
Profitability, credit risk, and expansion remain open questions
The growth metrics are self-reported, and no valuation has been disclosed. Recurring revenue of US$3 million against an annual volume of US$1.5 billion confirms that collections alone generate little margin. The investment case depends on guarantees and advances scaling; for an investor, 390% retention is a strong signal, but for an operator, it may reflect a very small initial base.
Guarantees and advances make Palomma a credit risk-taker. With high interest rates and a slow-growing economy, tenant delinquencies could rise, and the partnership with an insurer, which has yet to be finalized, would be key to avoiding having to absorb those losses alone. At the same time, the partnership would create dependence on a partner and reduce some of the margin that underpins the model.
Expansion raises another question. The company is prioritizing winning in Colombia, where it faces financial groups with balance sheets, licenses, and decades-long relationships with real estate agencies. In Mexico and Brazil, rental legal frameworks, payment rails, and local competition differ; replicating the efficiency of an 18-person team across three new markets will be an execution test.